Our Story
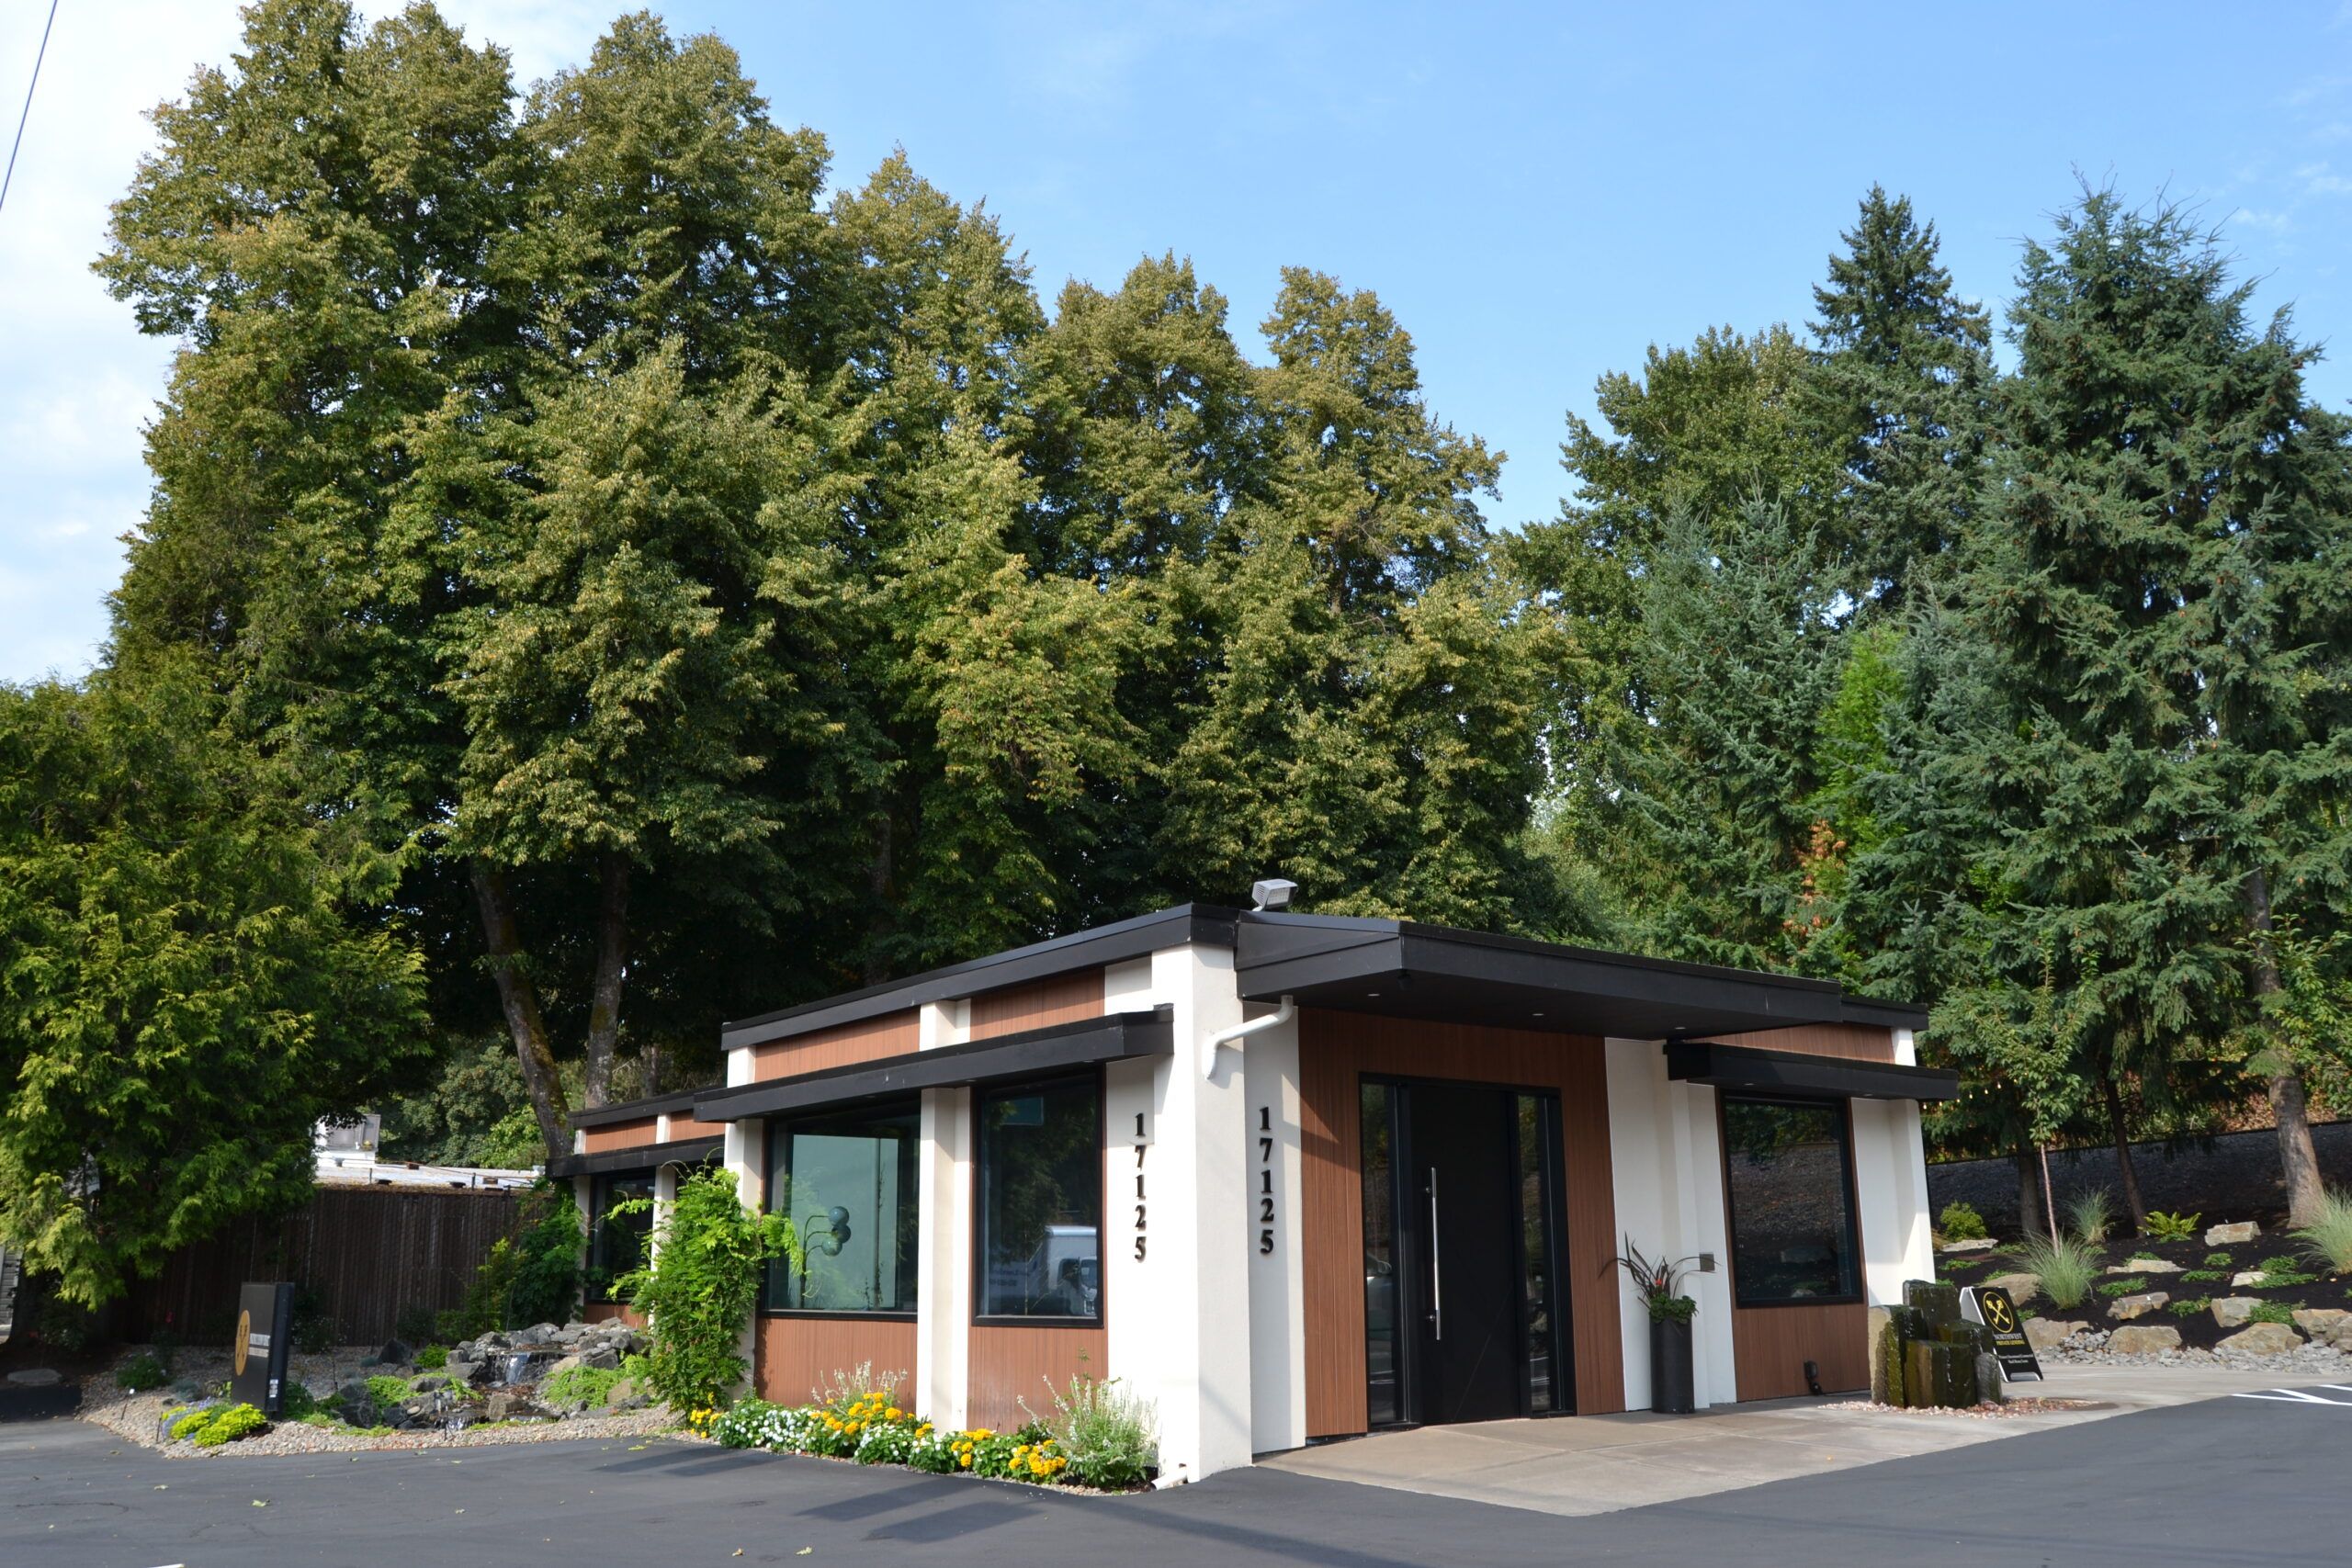
Our New Loan Office Is Making Local News
NW Private Lending’s New Office Sparks Local Interest In a move that’s turning heads across the real-estate investing community, Lake Oswego-based family office…
December 8, 2025
5 min read
Serving communities across the Pacific Northwest for nearly 40 years.
We specialize in asset-based loans on residential and commercial properties, including primary residences in Oregon and Idaho.
No hidden fees, no surprises. Here is what you will pay. Owner-occupied loans available in Oregon and Idaho only.
No junk fees, now or in the future. What you see is what you pay. We have built our reputation on transparency.
Get a Quote
With 150+ five-star Google reviews across three locations, our clients consistently praise the same things: speed, simplicity, honesty, and genuine care.
We are a family office, not an institution. Relationships are the foundation of our business.
Same-day approvals and closings in 3–5 business days on non-owner-occupied loans. When you find the right property, timing matters.
No extension fees. No pre-payment penalties. 3 points + document preparation up front, 1% per month interest payments. Pay off early with no penalty, or extend for free when the loan is in good standing at maturity.
Headquartered in Portland/Lake Oswego with offices in Boise/Meridian and Seattle/Bellevue. We know these markets because we live in them. Local expertise, local decisions.
From investment homes to commercial buildings, we offer equity-based loans across Oregon, Washington, and Idaho. Owner-occupied loans are available in Oregon and Idaho only; in Washington, we make business-purpose loans on non-owner-occupied property.
Hard money fix-and-flip loans with up to 80% of purchase price, no prepayment penalties, and same-day pre-approval for real estate investors.
Generally 2 years; free extensions in good standing
Typical Term
Speed isn't just a promise — it's built into every step of our process. Here's how we get you funded, fast.
On the ground
From idea to investment, we are here with you every step of the way.
Talk to a real person, not a call center. Let us know what you need and we will let you know if we can help.
Day 1We review the property and loan request. Same-day approvals are standard. No income verification or credit check required.
Day 1From loan application to loan documents our team will work with you, title, & escrow to collect what we need to make your loan.
Days 2–4Sign, fund, get your keys or cash. Non-owner-occupied, 3–5 business days. Owner-occupied, 7–10 business days (Oregon and Idaho only).
Days 3–5
Don’t take our word for it. Our clients consistently highlight the same things: speed, transparency, and genuine care.
Read all reviews“They took me at my word. Difficult to find these days. Eric and his team made the entire process seamless — from approval to closing in under a week.
“Everyone at Northwest Private Lending is wonderful to work with. They are good at communicating and this last purchase required a very quick close — they were ready two days before closing!
“Very professional and proficient through the whole process. Erik and Lizz were very helpful, explaining every step and making sure we understood each one. Communication was great throughout.
“NW Private Lending genuinely cares for your success as a person first. Eric Larson is a wonderful person who lent based on knowledge, experience, and above all — faith and trust.
Local expertise, local decisions. Visit us at any of our offices in Oregon, Idaho, or Washington.
Eric Larson, President
Erik Keyes, Regional Director
Jason Rubadue, Regional Director
NW Private Lending’s New Office Sparks Local Interest In a move that’s turning heads across the real-estate investing community, Lake Oswego-based family office…
📈 Mortgage Interest Rates Are Finally Dropping! Interest rates are finally falling again — and the market is paying attention.After…
Competition in Washington’s real estate market is fierce—especially around Seattle, Tacoma, Bellevue, Spokane, and the Tri-Cities. Properties move fast, multiple…
We believe in transparency in everything — including answering your questions before you even have to ask.
Have a question not listed here? Call us at 503-941-5473
A hard money loan is a short-term real estate loan made mainly on the property, not on your paycheck or credit history. "Private" describes where the money comes from: private capital instead of a bank. "Hard money" describes how the loan is made: against the real estate. At Northwest Private Lending, every borrower sees the same published pricing.
Private money describes the source of the capital: cash from private individuals rather than a bank. Hard money describes the kind of loan: an asset-based loan, where the lender looks first at the property and the equity in it. Most of the loans we make are both, which is why people use the two terms interchangeably.
We look first at the property, the equity in it, and your plan to repay. One question we ask is this: if the market dropped 30%, could the property still be sold and protect the money lent? That is how we think about risk, not a fixed rule or a guarantee. Because the loan rests on the property, situations that can stop a bank loan, such as a new job, a gap in work, a divorce, or a past bankruptcy, do not automatically rule you out. We still review the whole picture, and every loan follows the state and federal lending laws that apply to it. For how points, LTV, interest-only, and maturity work, see common hard money loan terms.
Many bank and conventional loans are written to set guidelines so they can be sold or insured, so the borrower and the property have to fit a box. Our loans are not packaged to be resold, so we can make an individual decision on a property or a situation that a bank's guidelines would not fit. That flexibility still works within the lending laws that apply, including consumer, occupancy, and licensing rules. Our conventional versus hard money FAQ walks through the comparison.
Our loans are funded with private capital that stays at risk for the life of the loan, with no government insurance on repayment. That is why a hard money loan costs more than a 30-year mortgage. We publish one price list for every borrower. Loan origination is 3 points (3% of the loan amount) with a $2,500 minimum. Interest is 1% per month (12% a year), interest-only. The loan document fee is $650 on non-owner-occupied loans, or $850 on owner-occupied loans in Oregon and Idaho. There is no underwriting fee, no required appraisal, $0 in required reserves, never a prepayment penalty, and a $0 extension fee on performing loans. On a $100,000 loan, that is a $3,000 origination fee and about $1,000 a month in interest. On a $500,000 loan, that is a $15,000 origination fee and about $5,000 a month. The full schedule is on What Are NWPL Rates and Terms?.
A hard money loan is the right tool only when you need it. Two things should be true. First, there is no better bank option. Second, there is meaningful equity in the property or a meaningful down payment. If a bank can make your loan, take the cheaper bank loan. Hard money fits when you need a fast close on an investment property, when a bank will not lend on the house yet, when you are bridging from one property to the next, when you need a short-term cash-out refinance, or when your circumstances do not fit a bank's guidelines right now. See when you should use hard money and pros and cons of hard money.
Owner-occupied loans are available in Oregon and Idaho; in Washington, we make business-purpose loans on non-owner-occupied property only. Owner-occupied loans use the same 3 points and 1% per month, with the $850 document fee, generally a 5-year maturity, and typically close in 7 to 10 business days. Details are on closing costs and owner-occupied loans.
Fix and flip, rehab and refinance, bridge, cash-out, commercial and industrial, 1031 and reverse 1031, acquisition, ITIN, and in-process construction loans, generally from $50,000 to $2,000,000. We do not offer ground-up construction loans. Browse the loans we offer or start with fix and flip and bridge loans.
Call or apply, we review the property and your plan, and approval is often same-day. Investor loans typically close in 3 to 5 business days once title and insurance are ready (how fast we close). Call 503-941-5473, Monday through Friday, 9am to 5pm PT. You can also pre-qualify online, apply for a loan, or send us a message.
Northwest Private Lending is a family private office that began in 1987 as Clunas Funding Group and rebranded to Northwest Private Lending in 2016. Our offices are in Portland, Boise/Meridian, and Seattle/Bellevue.
Private lenders are individuals, family offices, and private companies that lend private capital, usually secured by real estate, instead of lending depositors' money the way a bank does. A private money loan is the loan a private lender makes: a short-term real estate loan approved mainly on the property, your equity, and your plan to repay. We are a family office private lender in Oregon, Washington, and Idaho.
Private lenders come in a few forms:
Because the money is private, each lender sets its own standards, terms, and pace. That is the main reason private lending can say yes to a property or a situation that does not fit a bank's guidelines. It is also why private money costs more than a bank loan: the capital stays at risk for the life of the loan, with no government insurance behind it.
A private money loan is secured by a lien on real estate. It is usually interest-only and short-term, and it is repaid when the property sells or is refinanced into a bank loan. The lender looks first at the property, the equity in it, and your exit. On investor loans, credit score and income are not what drive the decision.
Private money and hard money are closely related. Private describes where the money comes from. Hard money describes how the loan is made: against the property. Most of the loans we make are both, which is why people use the terms interchangeably. Read what is a hard money loan or private money vs. hard money for more.
We are the direct lender. The people you talk with are the people who review, approve, and fund your loan, so there is no loan committee and no broker in between.
Our private money loans generally run from $50,000 to $2,000,000. Non-owner-occupied loans are generally written for 2 years and typically close in 3 to 5 business days. There is never a prepayment penalty, and when a loan is in good standing at maturity, there is no fee to extend it. Every borrower gets the same published pricing, listed on our rates and terms page.
We make private money loans on investment real estate across Oregon, Washington, and Idaho. Owner-occupied loans, including loans on primary residences, are available in Oregon and Idaho only. In Washington, we make business-purpose loans on non-owner-occupied property only. Our where we lend FAQ lists the markets we serve in each state.
Private lenders vary widely, so ask every lender the same questions and get the answers in writing:
Our answers are published: no underwriting fee, no required appraisal, $0 in required reserves, no prepayment penalty, and no extension fee on performing loans. You can read what our clients say on our reviews page.
We are a family office that began in 1987 as Clunas Funding Group and rebranded to Northwest Private Lending in 2016. Across those years, our family has closed 3,000-plus loans and $690 million-plus in financing for borrowers in the Northwest.
To talk through a private money loan, pre-qualify online, apply for a loan, or call us at 503-941-5473, Monday through Friday, 9am to 5pm PT. Our offices are in Portland/Lake Oswego, Boise/Meridian, and Seattle/Bellevue.
A hard money loan should only be considered when accessing capital now provides greater value or profit than the interest costs. All loans should be comfortably affordable monthly and used to purchase assets that generate income or provide long-term value.
Here are seven key assessment questions:
1. Timeline Need: If closure within 10 days is required, hard money works since private lenders focus on property equity without lengthy appraisals or inspections. Otherwise, banks offer competitive rates with 45-60 day timelines.
2. Primary Residence: Conventional loans suit primary residences in most cases. Hard money applies to investment properties like rentals or flips.
3. Loan Duration: Hard money is not ideal for long-term needs (rates range 9-15%). For short-term requirements, hard money compensates for higher rates through capital accessibility. At NWPL, business-purpose (non-owner-occupied) loans are generally written for 2 years, and owner-occupied loans (Oregon and Idaho only) generally for 5 years. When a loan is in good standing at maturity and you want to keep it longer, we extend it for free.
4. Exit Strategy: Properties planned for sale or refinance within 24 months align with hard money terms. Longer holds warrant conventional amortized loans.
5. Cash Purchase Goals: Hard money enables cash-like offers for foreclosures and distressed properties purchased below market value.
6. Retirement Account Repayment: If repaying borrowed retirement funds, a 12% hard money loan becomes attractive versus potential 60% tax penalties.
7. Real Estate Equity: Hard money requires existing real estate collateral. Those real estate-rich but cash-poor benefit from quick equity access.
Northwest Private Lending is a family office private lender in Oregon, Washington and Idaho, and every borrower gets the same pricing. Here is the full list:
A point is 1% of the loan amount. Three points is 3% of the amount you borrow, charged once at closing as the loan origination fee. It is figured on the loan amount, not on the purchase price or the property value.
Add the document fee and you have everything NWPL charges to make the loan. A $100,000 non-owner-occupied loan carries $3,650 in NWPL fees at closing and $1,000 a month in interest. A $500,000 loan carries $15,650 at closing and $5,000 a month. Title insurance and escrow closing costs are separate third-party charges from the title company and escrow — they are not included in the 3% origination fee — and recording and other third-party costs are disclosed before you sign.
A $60,000 loan takes about the same work as a $600,000 one: we review the property, talk through your plan, work with title and escrow, and prepare and fund the loan. At 3%, any loan under about $83,333 would earn less than $2,500, so the minimum applies to those smaller loans. On a $50,000 loan, for example, the origination fee is $2,500, which works out to 5% of the loan. We would rather tell you that up front than surprise you at closing.
Private money loans are priced differently from a 30-year bank mortgage. A bank spreads its costs over decades of payments. Our bridge loans, fix and flip loans and other real estate investment loans are usually paid off in months, or within about two years, so the cost of making the loan is collected once, at closing. The origination fee is paid to Northwest Private Lending and covers everything related to originating your loan in-house: the paperwork, evaluating the property ourselves instead of ordering an appraisal, underwriting the deal, and keeping the people who decide on your loan available for same-day approvals and 3–5 business day closings. Title insurance and escrow closing costs are separate third-party charges from the title company and escrow, and they are not included in the 3%. Monthly interest is the return on the family office capital that funds your loan. We do not add underwriting, processing or extension fees on top.
We also make owner occupied hard money loans in Oregon and Idaho, including loans on primary residences. They use the same 3 points and 1% per month, with an $850 document fee, generally a 5-year maturity, and typically close in 7–10 business days. In Washington we make business-purpose loans on non-owner-occupied property only.
Because we practice asset-based lending, approval turns on the property's equity and your plan, not your credit score. Call 503-941-5473 and we will run the numbers on your deal with you.
A private money loan involves borrowing from an individual or business lending their own saved capital or borrowed funds. Unlike banks that lend depositors' money, private lenders are just people like you who set their own loan terms and requirements.
Private lenders commonly overlook credit scores, back taxes, and bankruptcies that would disqualify conventional borrowers. Loans are typically secured by valuable assets, most commonly real estate through a lien arrangement.
Benefits include flexible qualification standards, faster approval processes, and customized loan terms.
Borrowers should work with trustworthy lenders and check references or reviews before borrowing.
Northwest Private Lending brings nearly 40 years of family-office lending that has financed nearly seven hundred million dollars since 1987. Clunas Funding Group was rebranded as Northwest Private Lending in 2016 and lends $50,000 to $2,000,000 per loan on investment real estate in Oregon, Washington, and Idaho, with transparent practices and fair treatment of borrowers.
Underwriting for hard money loans evaluates lending risks based primarily on property collateral value rather than borrower creditworthiness. The process involves five key components:
1. Property Evaluation: Assessment of the property's value, condition, and marketability to determine suitability as collateral through appraisals and inspections.
2. Loan-to-Value Ratio (LTV): Hard money lenders typically advance a percentage of property value, with lower ratios reducing lender risk through larger equity cushions.
3. Borrower's Equity: Though asset-based, lenders consider the borrower's equity stake as an indicator of commitment and risk reduction.
4. Exit Strategy: Lenders assess how borrowers plan repayment through property sales, traditional refinancing, or alternative funds.
5. Terms and Conditions: Final loan structure including interest rates, fees, and repayment schedules are determined based on assessed risk factors.
Underwriting for hard money loans is a more streamlined process compared to traditional loans, with a focus on the value and marketability of the collateral property.
Northwest Private Lending secures every private capital loan with real estate. That collateral approach is the foundation of nearly seven hundred million dollars in loans funded across more than three thousand loans to borrowers in Oregon, Washington, and Idaho.
Real estate serves multiple purposes in hard money lending. First, it leverages the intrinsic value of real estate assets to empower borrowers pursuing investment goals. Second, the diversity of acceptable property types — residential homes, commercial buildings, and vacant land — allows the lender to serve a broad spectrum of borrowers and financing needs, from property renovations to development ventures.
By requiring real estate collateral, hard money lenders mitigate risk while enabling borrowers to access capital quickly for various real estate investment strategies.
Hard money loans are asset-based, with underwriting decisions primarily focused on the equity or value of the property in which the loan is being made. These loans typically come from private lenders using their own capital and are commonly used for investment properties.
Hard money loan advantages include quick closing timelines (at NWPL, typically 3–5 business days for non-owner-occupied loans and 7–10 for owner-occupied loans in Oregon and Idaho), minimal documentation requirements, and flexible qualification criteria set by individual lenders rather than government standards. Disadvantages include higher costs due to private lenders determining their own interest rates, and lenders establishing their own repayment terms, requiring borrowers to carefully review agreements.
Conventional or conforming loans adhere to Fannie Mae and Freddie Mac guidelines. These standardized mortgages can be sold on secondary markets, enabling lenders to offer more competitive rates. Advantages include the lowest interest rates available for primary residence purchases and regulatory protections against predatory lending practices. Disadvantages include strict borrower requirements including strong credit scores, documented income history (1-2 years), and low debt levels, extended processing timelines (approximately 60 days), and required property appraisals.
Fill out the form and our team will review your deal — typically responding within a few hours. Or reach out directly:
503-941-5473
Mon–Fri, 9am–5pm PT
info@nwprivatelending.com
We respond within hours
Portland/Lake Oswego, OR
Seattle/Bellevue, WA • Boise/Meridian, ID